ETS2 delayed to 2028: what it means for shippers in road transport
Delaying ETS2 to 2028 does not remove the carbon cost on diesel: it gives shippers time to compare decarbonisation alternatives before it hits.
ETS2: what the delay to 2028 actually changes
ETS2 is the European carbon market that is set to apply to fossil fuels used in road transport and buildings, alongside the existing ETS system for heavy industry and aviation. Its entry into force, initially expected earlier, has been postponed to 2028, according to the AUTF in an article published on January 22, 2026.
The mechanism operates upstream: fuel suppliers and market operators are directly required to purchase emission allowances, not the road hauliers or the shippers that use their services. In practice, it is oil companies and fuel distributors that will need to cover the emissions linked to placing diesel, petrol or gas on the market.
This two- to three-year delay changes nothing on substance: the principle remains to build a rising carbon cost into the price of fossil fuels. What it does change is the timeline shippers need to prepare for, and therefore the window available to adjust their transport purchasing strategy.
Shippers do not pay ETS2 directly, but they absorb its cost
The fact that the obligation sits with fuel suppliers does not mean shippers will be spared. The carbon cost flows mechanically through the whole chain: the supplier passes its allowance cost into the fuel price, that price feeds diesel indexation clauses in transport contracts, and the indexation ultimately translates into a higher price paid by the shipper.
Fuel supplier → carbon cost → fuel price → indexation → transport price → shipper: this is the chain to keep in mind, rather than expecting a distinct 'ETS2' line on invoices. The cost will not appear separately; it will be absorbed into the diesel price and channelled through the contractual mechanisms already used to pass on fuel variations.
ETS2 will not create a new invoice line, it will make an existing one heavier: the fossil fuel line, through indexation clauses already in place.
What impact on road transport prices, in figures?
According to AUTF, the regulatory mechanism envisaged between 2028 and 2030 could correspond to an average impact of around 15 cents per litre of diesel. This figure should be read as an indicative order of magnitude, not a guaranteed forecast: it will depend on the actual carbon allowance price and on any cushioning mechanisms introduced at European or national level.
For a fleet consuming several hundred thousand litres of diesel a year, such a gap quickly translates into tens of thousands of euros in additional annual cost, even before any other movement in oil prices. For a multi-year transport contract, this is a parameter that now needs to be built into cost assumptions, alongside the underlying fuel price trend.
Beyond 2030, AUTF notes that a significant rise in the carbon price could make fossil fuel costs an even bigger driver of road transport pricing. The delay to 2028 therefore only postpones the deadline: it does not flatten the underlying trajectory of the carbon cost applied to diesel.
The delay mainly buys time to weigh up several levers
The main benefit of this delay is not to postpone the decision, but to open a window for comparing available decarbonisation levers before the carbon cost becomes binding. AUTF notes that a shipper has several options, which are not mutually exclusive and can be combined depending on the flows involved.
- alternative fuels (HVO, B100, bio-CNG) for existing fleets
- electrification of flows where distances and infrastructure allow it
- route optimisation and load-factor improvement
- logistics pooling between shippers
- modal shift to rail or inland waterway on suitable corridors
These levers do not have the same implementation timeline: modal shift and electrification require investment and infrastructure, while alternative fuels can often be introduced progressively across existing fleets without replacing vehicles. This difference in implementation time should help determine the order of priorities before 2028.
Compare the total cost of strategies, not just the ETS2 cost
The real question for a shipper is not to guess precisely how much ETS2 will cost, but to compare the total cost of several decarbonisation strategies against a diesel price set to rise. This means moving beyond a price-per-litre comparison to look at all the factors that determine a solution's real competitiveness.
- fuel cost and the foreseeable trend in its associated carbon cost
- total cost of ownership (TCO) of transport over the contract period
- actual fuel availability across the relevant operating regions
- compatibility with the existing fleets of partner carriers
- the actual CO₂ emission reduction achieved
- traceability and the ability to provide evidence for CSRD-type reporting
Turn ETS2 into a competitive advantage
Postponing this comparison until 2028 means being driven by the calendar rather than getting ahead of it. Shippers who start testing these criteria now, on part of their flows, will have concrete data in hand once the carbon cost becomes effective, rather than discovering the issue under regulatory pressure.
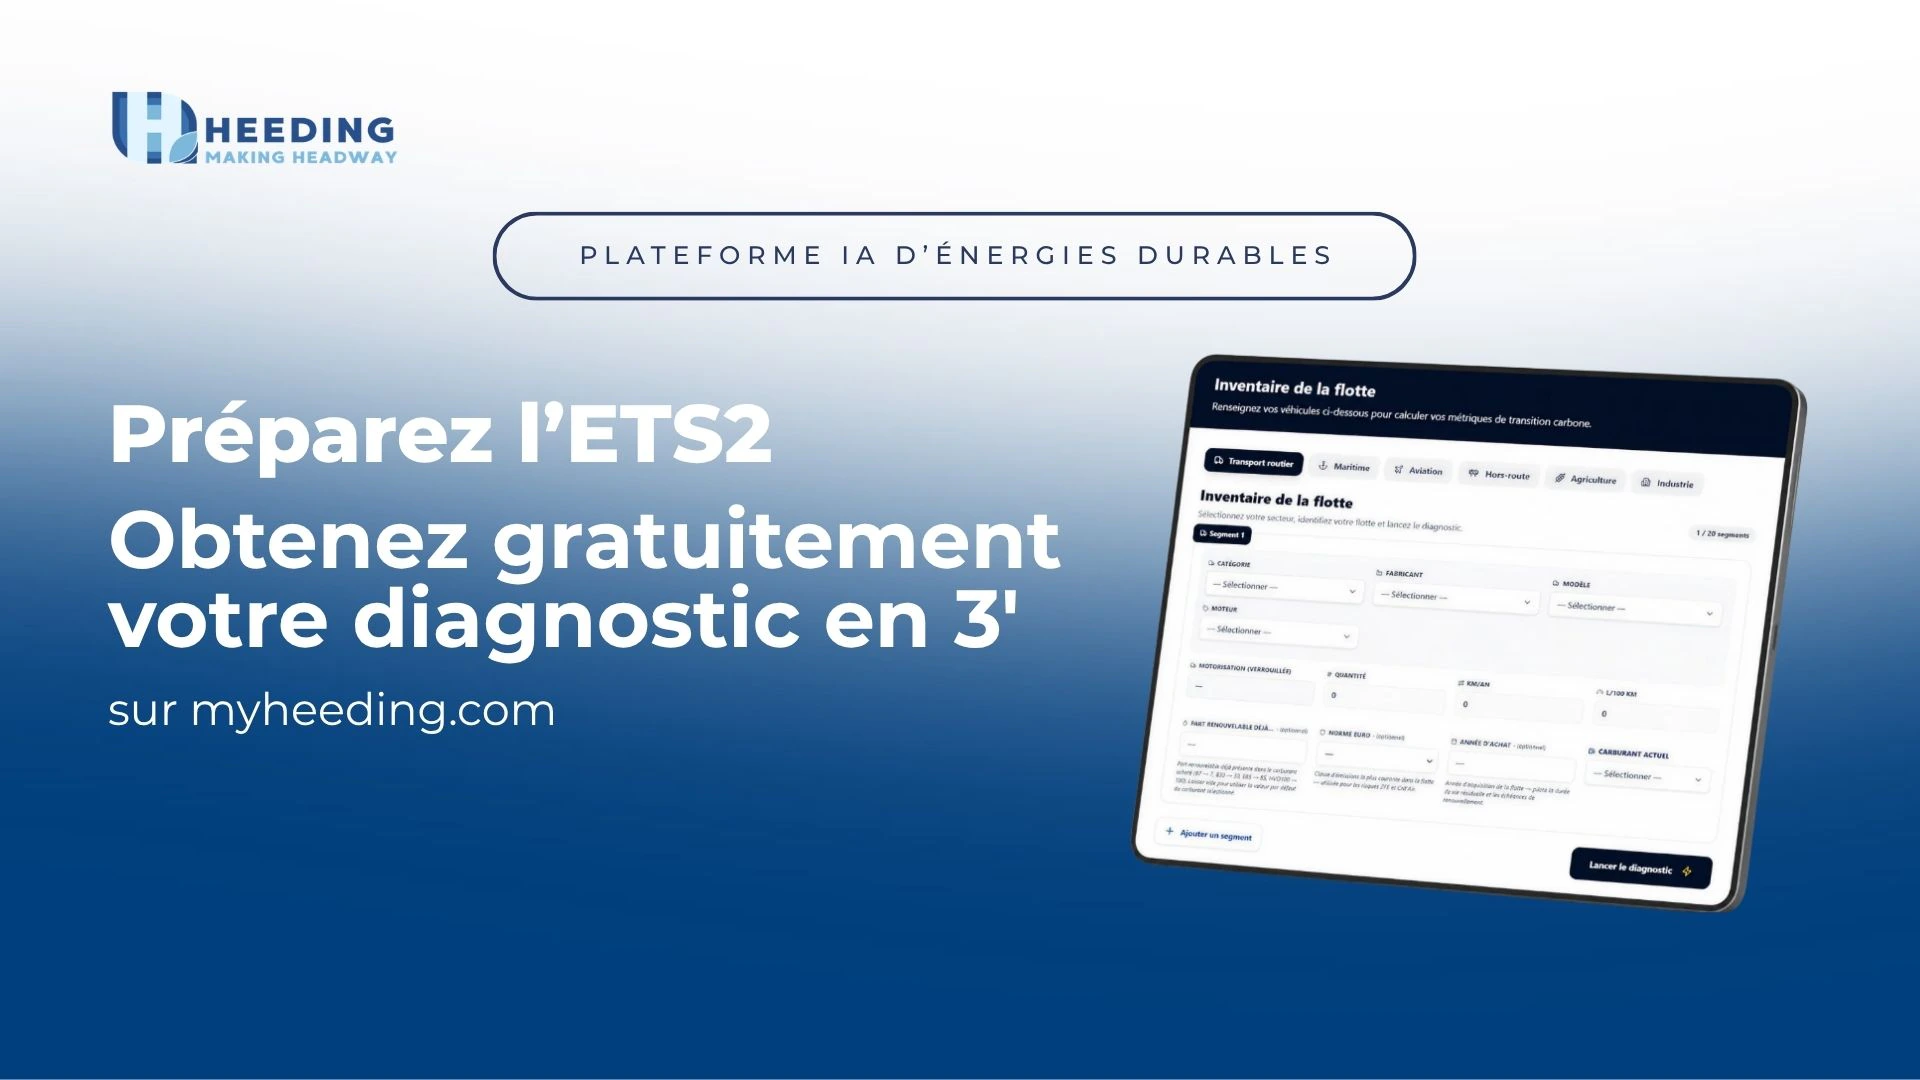
Heeding supports you in choosing the right transition strategy through its Flash Diagnostic, which helps identify the most relevant solutions for your fleet and operations. The goal is not to impose a specific technology, but to help you determine which option best fits your situation and timeline.
Once you have made your choice, finding and purchasing sustainable fuels at the best available price becomes much simpler. No more endless calls and exchanges to find a supplier, collect certificates or compare offers: Heeding brings producers and distributors together on one platform, allowing you to compare prices and availability, place orders directly and retrieve your traceability documents in one place.
Create your free Heeding account and start comparing available offers today.